
The Psychological Power of Family Rituals in Cultivating Emotional Security
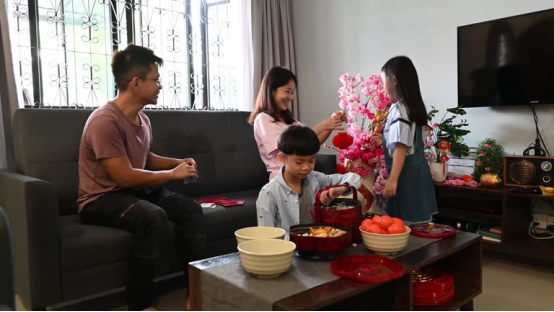
In the complex landscape of child development, emotional security serves as the bedrock upon which all other cognitive and social skills are built. Family rituals go far beyond mere daily routines; they are deeply symbolic behaviors that provide children with a profound sense of identity, belonging, and psychological safety. While a routine is a sequence of actions regularly followed, a ritual carries emotional weight and meaning. When children can predict positive, emotionally resonant interactions with their caregivers, their baseline cortisol (stress hormone) levels stabilize. This predictability acts as a psychological anchor, especially crucial during times of external transition, such as starting a new school, moving to a new neighborhood, or navigating the turbulent waters of adolescence.
Understanding the Mechanics of Predictability
The human brain, particularly in its early developmental stages, is highly attuned to pattern recognition. When a family establishes a consistent ritual—whether it is a specific way of saying goodbye in the morning or a dedicated Friday night pizza and board game tradition—the child’s brain registers this pattern as a safe haven. This neurological safety net allows the child to redirect cognitive energy away from anxiety and hyper-vigilance toward exploration, learning, and emotional regulation. Children who grow up in households with strong, positive rituals demonstrate higher resilience when facing adversity, as they possess an internalized belief that regardless of the chaos in the outside world, their family unit remains a stable, unwavering sanctuary.
- Identity Formation: Rituals communicate to children that they are part of a unique tribe with its own inside jokes, traditions, and values, fostering a strong self-concept.
- Emotional Regulation: The predictability of recurring family events helps children manage their expectations and soothe their own nervous systems during periods of distress.
- Intergenerational Connection: Passing down rituals from grandparents or cultural backgrounds roots the child in a broader historical context, expanding their worldview and sense of place.
Implementing Micro and Macro Rituals
Effective family rituals do not require immense financial investment or exhaustive planning; rather, they rely on intentionality and consistency. Micro-rituals are small, daily touchpoints that reinforce connection. Examples include a specific handshake before getting on the school bus, a consistent bedtime story routine accompanied by a specific lullaby, or sharing the “rose and thorn” (the best and worst parts) of the day around the dinner table. Macro-rituals are larger, less frequent events that punctuate the calendar, such as annual camping trips, baking specific recipes on holidays, or celebrating half-birthdays. Both macro and micro rituals work in tandem to weave a tight fabric of familial trust. When parents actively protect these times from digital distractions and work obligations, they send a powerful, unspoken message to the child: “You are my priority, and our connection is sacred.”

Bridging Emotional Security with Practical Life Skills
There is a profound, often overlooked intersection between a child’s emotional security and their ability to grasp complex, practical life skills such as financial literacy. A child who feels emotionally secure is inherently more capable of practicing delayed gratification—a cornerstone of financial responsibility. When children trust that their basic emotional and physical needs will consistently be met by their caregivers, they do not operate from a mindset of scarcity. This abundance mindset, fostered by the family rituals discussed previously, creates the ideal psychological environment for introducing the concepts of saving, budgeting, and understanding the intrinsic value of money.
The Scarcity vs. Abundance Mindset in Early Development
Children raised in environments lacking predictable emotional support often struggle with impulse control. If a child subconsciously believes that good things are fleeting and unpredictable, they are highly likely to demand immediate gratification when presented with resources, including money. Conversely, a secure child can internalize the concept of waiting. They understand that if they delay purchasing a small toy today, the promise of a larger, more desirable reward in the future is reliable. Therefore, establishing family rituals and building emotional trust is the prerequisite groundwork before handing a child their first piggy bank or allowance.
Introducing the Concept of Value
Teaching children the value of money begins long before they understand currency denominations. It starts with teaching the value of effort, time, and resources. Parents can integrate financial literacy seamlessly into existing family rituals. For instance, if a family has a ritual of grocery shopping together on Sunday mornings, this becomes a prime opportunity to narrate financial decision-making out loud. Comparing the unit prices of two different brands of cereal, explaining why a generic brand might be chosen over a heavily marketed one, or discussing how a coupon works transforms a mundane chore into an immersive, real-world classroom. The goal is to demystify money, removing any taboo surrounding financial discussions and replacing it with transparent, age-appropriate education.

Teaching Children the Value of Money: A Step-by-Step Framework
To effectively teach children the value of money, parents must transition from abstract concepts to tangible, experiential learning. Children are highly tactile and visual learners; therefore, abstract discussions about credit scores or retirement funds will not resonate. Instead, financial education must be broken down into actionable, developmentally appropriate stages that allow children to make low-stakes financial mistakes under the protective umbrella of their parents’ guidance.
The Allowance Dilemma: Tied to Chores or Independent?
One of the most debated topics in parenting is whether an allowance should be tied to household chores. Financial experts and child psychologists often recommend a hybrid approach to maximize learning. Providing a small, unconditional base allowance teaches children how to manage a predictable income stream, allowing them to practice budgeting, saving, and giving. Simultaneously, parents can offer “commission-based” extra chores—tasks outside the realm of basic family responsibilities (like washing the car or pulling weeds). This hybrid model teaches two distinct lessons: first, that as a member of the household, you have basic duties that are unpaid (making your bed, clearing your plate); second, that going above and beyond yields financial reward, directly connecting effort to earning power.
- The Spend, Save, Give System: Instead of a single piggy bank, utilize three clear jars labeled “Spend,” “Save,” and “Give.” This visually reinforces that money has multiple purposes. When a child receives their allowance, they must divide it among the jars based on predetermined percentages (e.g., 50% spend, 40% save, 10% give).
- Goal Setting and Matching: Encourage children to set specific financial goals for their “Save” jar. To incentivize long-term saving, parents can act as an “employer” and offer a matching program. For example, for every dollar the child saves toward a new bicycle, the parent matches it with fifty cents. This introduces the concept of employer-matched retirement funds early in life.
- Needs vs. Wants Exercises: Regularly engage children in categorizing items. While at the store, ask them to identify if an item is a need (like winter boots) or a want (like a designer jacket). This critical thinking exercise builds the cognitive muscle required for adult budgeting.

Advanced Strategies for Long-Term Financial Literacy
As children mature into pre-teens and adolescents, their financial education must evolve to match their growing independence and cognitive capabilities. The foundational lessons of the three-jar system must transition into digital banking, understanding debt, and recognizing the psychological triggers of consumerism and targeted advertising. Parents must act as financial mentors, guiding their teenagers through the complexities of the modern economic landscape while continuing to model healthy financial behaviors themselves.
Age-Appropriate Financial Milestones
Structuring financial education by age ensures that the child is neither overwhelmed by complexity nor bored by simplicity. The following framework provides a roadmap for parents to scale their financial lessons appropriately as their child grows.
| Age Group | Core Financial Concepts | Actionable Parenting Strategies |
|---|---|---|
| Ages 4-6 | Identifying coins, understanding that money is exchanged for goods, waiting to buy. | Use clear jars for saving. Play “store” at home with fake money. Let them hand cash to cashiers. |
| Ages 7-10 | Opportunity cost, basic budgeting, earning through extra chores, needs vs. wants. | Implement the hybrid allowance system. Have them pay for their own “wants” with their “Spend” jar. |
| Ages 11-14 | Compound interest, digital banking, comparison shopping, recognizing advertising. | Open a joint teen checking/savings account with a debit card. Discuss the family budget openly. |
| Ages 15-18 | Credit vs. Debit, investing basics, taxes on paychecks, saving for major goals (car/college). | Help them get a part-time job. Explain how credit cards work and the dangers of high-interest debt. |
Navigating the Digital Economy and Consumerism
Today’s youth are bombarded with micro-targeted advertisements and the frictionless ease of digital spending. In-app purchases, one-click online shopping, and digital wallets can make money feel invisible and infinite. To counter this, parents must actively teach the concept of “invisible money.” When using a credit card or digital payment, explicitly state to the teenager, “I am using this card, which pulls real money from my bank account to pay the merchant.” Furthermore, discuss the psychology of marketing. Analyze commercials together and ask, “What is this advertisement trying to make you feel? Why do they want you to buy this right now?” By fostering a healthy skepticism toward consumerism, parents empower their children to make intentional, value-based purchases rather than impulsive, emotion-driven ones.
Frequently Asked Questions (FAQ)
- How do family rituals directly impact a child’s anxiety levels?
- Family rituals create a predictable environment, which is highly soothing to a child’s developing nervous system. When children know exactly what to expect during key transition times (like mornings or bedtimes), their brain reduces the production of cortisol, the primary stress hormone. This neurological predictability allows them to feel safe, lowering baseline anxiety and improving emotional regulation.
- At what age should I start teaching my child about money?
- Financial education can begin as early as ages 3 to 4. At this stage, the focus is not on complex math, but on the basic concept of exchange—understanding that money is required to acquire goods. You can start by letting them physically hand cash to a cashier or by playing imaginative “grocery store” games at home to build foundational awareness.
- Should chores be tied directly to a child’s allowance?
- Most developmental psychologists and financial experts recommend a hybrid approach. Basic household responsibilities (like cleaning their room) should be expected simply as a contributing member of the family, without financial reward. However, parents can offer additional, optional tasks (like washing the car or organizing the garage) that are tied to a financial payout, teaching the direct correlation between extra effort and earning.
- What if our family schedule is too erratic for daily rituals?
- Rituals do not have to be time-consuming or rigidly scheduled to be effective. If you work erratic shifts, focus on “micro-rituals” that can happen anywhere, such as a special handshake, a specific phrase you say before parting, or leaving a sticky note in their lunchbox. The power of a ritual lies in its emotional consistency and meaning, not necessarily in it happening at the exact same time every day.
- How can I explain inflation or economic hardship to a young child without causing panic?
- Honesty coupled with reassurance is key. You can explain inflation using simple terms: “The cost of making things has gone up, so the prices at the store are higher. Because of this, our family is choosing to be extra smart with our money.” Reassure them that their basic needs—food, shelter, and love—are secure. Frame economic adjustments as a team effort, such as, “We are going to cook more fun meals at home instead of eating out, and we can all help pick the recipes!”
Parenting and child-care note: This article is for general education only. It is not medical diagnosis, pediatric care, mental-health therapy, sleep treatment, emergency guidance, or individualized developmental advice. For symptoms, injury, illness, vaccines, medication, psychological distress, developmental delay, or urgent safety concerns, consult qualified pediatric, mental-health, education, or emergency professionals.